Debt recovery services for banks help financial institutions manage overdue loan accounts, improve collection operations and recover outstanding dues through structured recovery programmes. For banks and non-banking financial companies (NBFCs), the right recovery partnership can support internal collections teams, provide additional operational capacity and improve the management of delinquent retail loan and credit card portfolios.
As lending portfolios grow, financial institutions must balance recovery performance, operating costs, customer communication and regulatory compliance. An effective debt recovery strategy combines clear processes, suitable borrower engagement, performance monitoring and accountable recovery partners.
Moneytor works with the institutional debt recovery and collections model, helping banks and financial institutions explore structured approaches to resolving overdue accounts. The right partnership depends on portfolio characteristics, recovery requirements and mutually agreed commercial terms.
What Are Debt Recovery Services for Banks?
Debt recovery services for banks are outsourced or partnership-based services that help lenders manage and recover overdue payments from borrowers. These services can support the recovery of outstanding personal loans, credit card balances and other eligible retail credit accounts.
Depending on the arrangement, a recovery partner may support account follow-ups, repayment coordination, case prioritisation, resolution workflows and recovery performance reporting.
The objective is to help banks manage delinquent accounts more effectively while maintaining appropriate controls over customer communication, information security and recovery practices.
Common areas of support include:
- Retail loan recovery: Managing overdue accounts across eligible personal loan and other retail credit portfolios.
- Credit card collections: Supporting the collection of overdue card balances through structured follow-up processes.
- Delinquent account management: Prioritising accounts according to their status, ageing and recovery requirements.
- Recovery operations support: Helping internal teams manage workloads and coordinate recovery activities.
- Portfolio-level recovery: Supporting defined recovery programmes for selected loan portfolios or stressed assets.
The scope of services should be agreed upon by the bank and its recovery partner, with clear responsibilities, performance measures and escalation procedures.
Why Do Banks Need Structured Debt Recovery Solutions?
Banks need structured bank debt recovery solutions because overdue accounts can require different approaches depending on repayment history, delinquency stage, portfolio type and borrower circumstances.
Managing every account through the same process can limit operational efficiency. Internal teams may also face capacity constraints when collection volumes increase or when a specific portfolio requires additional attention.
India’s banking data illustrates why recovery remains an important institutional function. According to the Government of India’s Ministry of Finance, the gross non-performing asset (GNPA) ratio of public sector banks declined from 9.11% in March 2021 to 2.58% in March 2025. The figures reflect improvements in overall asset quality, not the performance of any single recovery provider.
Even with improvements in asset quality, banks need processes to address overdue accounts, manage new delinquencies and handle stressed portfolios.
A structured recovery partnership can help institutions:
- Add operational capacity without relying entirely on internal teams.
- Organise accounts based on delinquency status and recovery priorities.
- Improve coordination between internal collections teams and external partners.
- Monitor recovery activity against agreed performance indicators.
- Establish consistent reporting and escalation procedures.
- Maintain oversight of customer communication and recovery conduct.
The value of a partnership should be evaluated using the lender’s own portfolio data, baseline performance and agreed commercial objectives.
Common Models of Debt Recovery Services for Banks
Banks can adopt different recovery models depending on their internal capabilities, portfolio requirements and risk policies. Not every model is suitable for every institution.
The following table outlines common approaches that banks and NBFCs can evaluate.
| Recovery model | How it works | Best suited for |
| In-house collections | The bank manages recovery through its own employees, systems and processes. | Institutions with established collections teams and infrastructure |
| Outsourced recovery support | An external agency supports defined recovery activities under the bank’s oversight. | Banks seeking additional operational capacity |
| Commission-based recovery partnership | Commercial compensation is linked to agreed recovery outcomes or another defined arrangement. | Institutions seeking an outcome-oriented commercial model |
| Portfolio-specific recovery programme | Dedicated workflows are designed for a particular loan category, delinquency stage or stressed portfolio. | Banks with distinct portfolio-level recovery requirements |
| Hybrid recovery model | Internal teams manage selected activities while external partners support specific stages or account segments. | Institutions balancing internal control with external capacity |
1. In-house debt recovery
In-house recovery gives banks direct control over staffing, workflows, customer communication and performance monitoring. However, it requires ongoing investment in personnel, training, systems and operational management.
2. Outsourced bank loan recovery services
Outsourced bank loan recovery services allow lenders to engage external partners for agreed activities. Banks should define the scope of work, account allocation, reporting requirements, quality standards and escalation responsibilities before onboarding a partner.
3. Commission-based recovery partnerships
A commission-based partnership ties compensation to agreed commercial terms, potentially including verified recovery outcomes. The arrangement should clearly define eligible accounts, how recoveries are attributed, payment calculations, reconciliation procedures and dispute resolution.
Moneytor’s institutional positioning centres on structured, outcome-oriented debt recovery partnerships. Specific commercial terms should be discussed and agreed upon with each institution.
Key Benefits of Bank Debt Recovery Solutions
The benefits of debt recovery services depend on portfolio quality, implementation, operational discipline and partner performance. Banks should assess these benefits against their own objectives rather than assume that outsourcing automatically improves recovery.
Improved recovery operations
A defined recovery programme can help organise account follow-ups, establish escalation procedures and ensure that overdue accounts receive attention according to agreed priorities.
This can be particularly relevant for lenders managing multiple retail credit products or large volumes of delinquent accounts.
Better use of internal resources
External recovery support can help internal teams focus on activities that require direct institutional oversight, complex account handling and portfolio-level decision-making.
The extent of any operational savings depends on the scope of outsourcing, the fee structure and the cost of managing the partnership.
Greater portfolio visibility
Structured reporting can help collections leaders understand recovery activity across account segments, delinquency stages and programme periods.
Useful reporting may include:
- Amount recovered against the eligible portfolio.
- Recovery rate against a defined outstanding balance.
- Account-level resolution status.
- Collection activity and contact outcomes.
- Cost per account or cost per unit recovered.
- Complaints, compliance exceptions and unresolved cases.
Each metric needs a consistent definition and reporting period so that performance comparisons remain meaningful.
Flexible recovery capacity
A recovery partner may provide additional capacity for specific portfolios or operational requirements. This can help banks evaluate alternative approaches without immediately expanding every part of their internal collections infrastructure.
Any proposed capacity or coverage should be validated during partner evaluation and programme planning.
Stronger accountability
Clearly defined service levels, documented responsibilities and periodic performance reviews help banks identify operational gaps and decide when a recovery programme needs adjustment.
Accountability should cover both financial outcomes and the quality and compliance of recovery activities.
Debt Recovery Strategies for Banks: What Should Lenders Evaluate?
Selecting the right recovery approach requires more than comparing service fees. Banks should evaluate the partner’s operational capabilities, reporting processes, compliance controls and ability to work within the institution’s requirements.
Segment accounts by delinquency stage
Banks can organise accounts using factors such as days past due, outstanding balance, repayment history and the applicable recovery strategy.
This helps institutions define suitable workflows for different account categories instead of applying an identical approach to every overdue account.
Establish clear recovery workflows
Each programme should define how accounts are assigned, how activities are documented, when cases are escalated and how resolution outcomes are recorded.
The workflow should also specify how disputed accounts, customer complaints and requests for further review are handled.
Define measurable performance indicators
Banks should agree on a measurement framework before the programme begins.
| Performance indicator | What it measures |
| Recovery rate | Amount recovered relative to a clearly defined eligible balance |
| Resolution rate | Share of assigned accounts reaching a defined resolution status |
| Cost per recovery | Programme costs relative to the amount recovered |
| Delinquency movement | Changes in account distribution across overdue stages |
| Contact effectiveness | Outcomes from documented collection interactions |
| Compliance performance | Complaints, policy exceptions and adherence to agreed procedures |
These metrics should be interpreted together. A higher recovery rate, for example, should not be evaluated without considering programme costs, account mix, time period and compliance performance.
Maintain regulatory and customer safeguards
Banks remain responsible for appropriate oversight of outsourced recovery activities. The Reserve Bank of India has issued requirements concerning regulated entities that engage recovery agents, including the responsibility of regulated entities for service providers’ actions.
Banks should verify applicable RBI directions, outsourcing requirements and internal policies when designing a recovery partnership. Controls should cover partner due diligence, staff training, authorised communication, customer data protection, complaint handling and auditability.
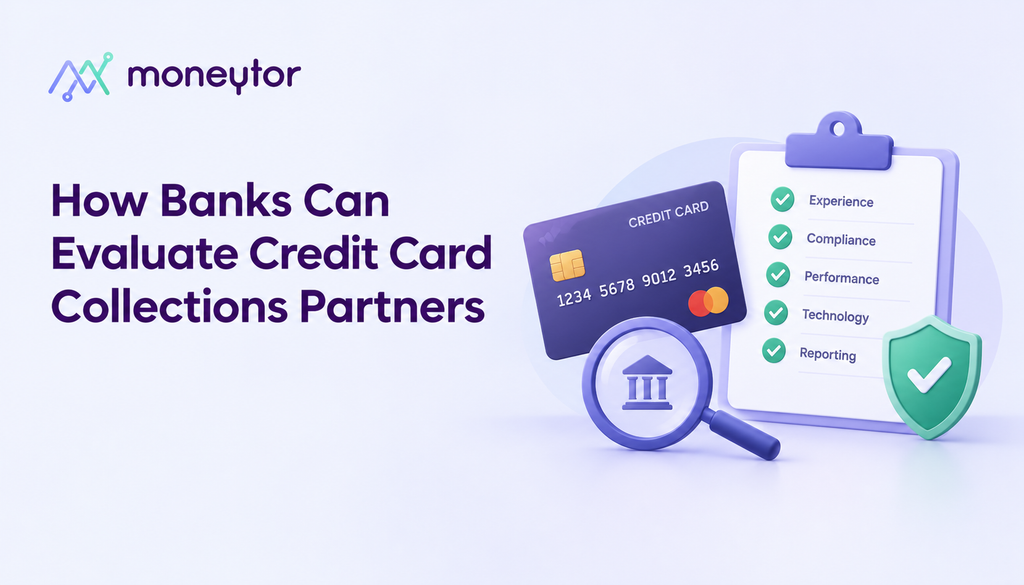
Key Considerations When Choosing a Debt Recovery Partner
Before selecting a partner, banks and NBFCs should conduct a structured assessment of operational suitability and commercial viability.
1. Relevant portfolio experience
Evaluate whether the provider can support the institution’s specific requirements, such as retail loans, credit card collections or selected delinquent account segments.
2. Compliance and governance
Review the provider’s due diligence processes, staff training, code of conduct, complaint escalation, information security and audit arrangements. Responsibilities should be documented in the agreement.
3. Reporting and reconciliation
Confirm how account activity, collections, resolution status and financial outcomes will be reported. Establish a process to reconcile recovery records with the bank’s systems.
4. Commercial transparency
Review the fee structure, eligible accounts, recovery attribution, payment terms, exclusions and dispute resolution process. Where compensation depends on outcomes, the calculation method must be clear to both parties.
5. Operational integration
Determine how the partner will receive authorised account assignments, submit updates and escalate cases. Data access should be restricted to approved purposes and appropriate security controls.
6. Performance review
Agree on baseline metrics, reporting frequency, review meetings and corrective actions. Avoid relying on headline recovery claims without a verified methodology and comparable portfolio data.
How Moneytor Supports Institutional Debt Recovery Partnerships
Moneytor focuses on debt recovery and collections partnerships for banks and financial institutions. Its institutional proposition is intended for lenders looking to explore structured approaches to outstanding retail debt and recovery operations.
A potential partnership should begin with an understanding of the institution’s portfolio, current recovery processes and operational priorities.
The discussion can cover:
- Portfolio requirements and eligible account categories.
- Existing collection workflows and operational constraints.
- Proposed recovery programme scope and responsibilities.
- Performance measurement and reporting requirements.
- Compliance, governance and escalation procedures.
- Commercial terms based on the agreed partnership arrangement.
The specific scope, operating model and expected outcomes should be established during institutional discussions. Any performance commitments should be based on documented assumptions, verified information and mutually agreed evaluation criteria.
For banks, NBFCs and lenders: Contact Moneytor to discuss your debt recovery requirements and explore a potential collections partnership.
Frequently Asked Questions
What are debt recovery services for banks?
Debt recovery services for banks help financial institutions manage overdue accounts and recover outstanding loan or credit card dues. Depending on the engagement, a provider may support account follow-ups, recovery workflows, portfolio-specific programmes and performance reporting.
How can banks benefit from outsourcing debt recovery?
Outsourcing may provide additional operational capacity, structured account management and access to defined recovery processes. The benefits depend on the portfolio, service scope, provider performance and commercial arrangement.
What is the difference between in-house and outsourced debt recovery?
In-house recovery is managed directly by the bank’s employees and systems. Outsourced recovery involves an external provider handling agreed activities under defined contractual, operational and compliance controls. A hybrid model combines both approaches.
How do banks evaluate a debt recovery partner?
Banks should assess portfolio experience, compliance controls, reporting quality, data security, operational capacity, commercial transparency and performance measurement. Due diligence should also cover staff training, complaint handling and audit requirements.
What is a commission-based debt recovery partnership?
A commission-based debt recovery partnership is a commercial arrangement in which compensation is linked to agreed terms, potentially including verified recovery outcomes. The agreement should define eligible accounts, attribution rules, calculation methods, reconciliation and payment terms.
Are banks responsible for outsourced recovery agents?
Banks must maintain appropriate oversight of outsourced recovery activities. RBI guidance establishes that regulated entities retain responsibility for the actions of their service providers. Institutions should verify the applicable regulatory requirements and maintain suitable governance controls.
Which financial institutions can explore debt recovery partnerships with Moneytor?
Banks, NBFCs, credit card issuers and other eligible financial institutions can explore whether Moneytor’s institutional debt recovery partnership model fits their portfolio and operational requirements. The suitability and scope of any engagement should be assessed directly.
How can a bank discuss a debt recovery partnership with Moneytor?
A bank or lender can contact Moneytor to discuss its portfolio requirements, recovery objectives, operating model and commercial expectations. The initial discussion should establish the proposed scope, performance measures and governance requirements.
Conclusion
Debt recovery services for banks can support more structured management of overdue retail loans, credit card balances and delinquent portfolios. The right model depends on the lender’s account mix, internal capabilities, compliance requirements and recovery objectives.
Banks and NBFCs should evaluate recovery partners on operational suitability, transparent commercial terms, measurable performance and strong governance, rather than on unsupported recovery promises.
Moneytor provides an institutional starting point for banks and financial institutions seeking to explore debt recovery and collections partnerships. Discuss your portfolio requirements with Moneytor to evaluate a suitable recovery programme.